Investor overview · Pre-seed · Confidential
The category is empty.The window is measurable.The founder has done this before.
AI School for Girls is the first paid, year-long, girls-only online AI school for ages 10–15 — a subscription education business built inside a documented developmental window that no incumbent can serve without breaking its own model.
The 30-second version
- What
- A year-long online AI school, girls only, ages 10–15. $99/mo founding ($149 standard), 36-week live school year, cohorts of 12 with the same teacher all year.
- Why now
- US occupations requiring AI fluency grew ~7× in two years while women's share of US computing has fallen to 26.7% — and 13% of US parents are opening a brand-new AI-education budget line this year. The pipeline breaks at age 11. We enroll at 10.
- Why us
- Founder's core skill is AI-powered customer acquisition at enterprise scale (15,250+ leads, 650 qualified appointments for an AI medical device). CAC discipline is her day job, not a future hire.
- Why empty
- Free programs (Girls Who Code) structurally can't charge; paid academies (iD Tech, Create & Learn) are co-ed drop-ins by design. Taking this seat requires incumbents to abandon their model.
- Economics
- Modeled contribution margin at capacity: ~54% founding / ~69% standard at midcase costs; 12M US girls in the age band means every 1% penetration is a $140–215M ARR business. One girl can re-enroll five years running — the NRR engine that separates venture subscriptions from lifestyle ones.
- The ask
- Pre-seed on a SAFE, sized to buy 12 months to one milestone: full cohorts with measured CAC, retention, and completion — the exact evidence a seed round prices on.
Pre-revenue, not pre-work
What already exists — click and check any of it
The school, built
36-week outcome-per-class curriculum across two age bands; founding cohorts forming now; free girls' intro workshops and live parent sessions run online.
The funnel, live
A 20-page site with nine instrumented capture funnels — workshop, quiz, parent guide, parent session, concierge chat, referral, sponsor-a-seat — every form tagged with lead-source attribution from day one.
The moat, poured
Privacy-first architecture already in production: parent-owned accounts, minimal child data, zero student-side trackers, no ads. The trust story isn't a slide — it's shipped.
Founding-cohort fill rate, CAC, and retention become real numbers within one quarter of the first cohort's start — the first datapoints a seed round will price on.
Why now
Two curves are moving in opposite directions. That scissors is the company.
Everyone knows AI demand is exploding. Fewer have noticed the other blade: American women's position in computing is lower today than it was in 1990.
Growth in US workers in occupations where AI fluency is explicitly required — in just two years.
McKinsey, via Gloat 2026 →Women's share of US computer-science degrees, 1985 to today — the pipeline cut nearly in half. Women now hold 26.7% of US computing jobs (BLS), down from a ~31% peak in 1990.
NSF/NCWIT, via Spacelift 2026 → · US BLS via Zippia, Feb 2026 →The break in that pipeline is documented and specific: girls' STEM interest peaks at age 11 and declines through 15, driven by confidence and belonging, not ability (Microsoft / NGCP / AAUW). Every year the scissors opens wider, the parent anxiety we sell into gets sharper — and whoever owns the trusted solution at age 10 owns the customer the whole way up.
AI moved into the home
Parents watched AI arrive in their own jobs in under three years. "Will my kid be ready?" is now a universal dinner-table question. Demand doesn't need creating — it needs a product.
The drop-off stayed unfixed
A decade of awareness programs proved the problem and the demand — mostly as nonprofits that structurally can't capture the value.
Live online is default behavior
Post-2020, parents pay for live small-group online classes without hesitation. Outschool proved the rails at a ~$3B peak valuation. The girls-only AI school on those rails doesn't exist.
Founder
Pre-seed is a bet on a person. Here's the person.
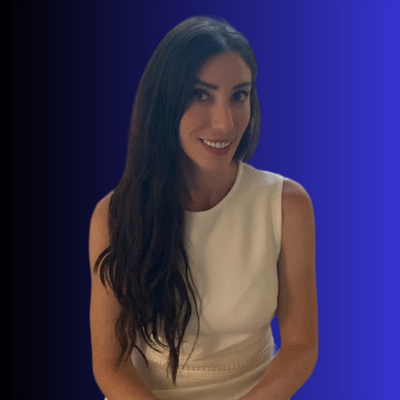
Mira Wattar
Founder & CEO · AI School for Girls · Founder, Wattar Digital · linkedin.com/in/mira-wattar
- Former VP of Global Marketing at EchoNous (AI medical devices): built the demand engine that produced 15,250+ physician/hospital leads and 650 qualified sales appointments for a hard technical product.
- Marketing leadership at Fujitsu Frontech North America and Hyundai Technology; founder of Wattar Digital, an AI-powered B2B demand-generation practice.
- Advisor at Loyal VC; mentor and speaker with the Founder Institute; operating history across D.C., Dubai, NYC, and California.
Business model
Subscription education, cohort-locked, camp-free
Revenue is a monthly subscription around a 36-week live school year. Cohorts cap at 12 — small enough that every girl presents every week, large enough for strong economics on contracted instructors.
| Per cohort, monthly (modeled) | Founding ($99) | Standard ($149) |
|---|---|---|
| Revenue at capacity (12 girls) | $1,188 | $1,788 |
| Instructor (contracted, ~5 hrs/wk loaded) | ~$400–600 | |
| Platform + tools | <$100 | |
| Contribution margin at capacity | ~41–62% | ~61–75% |
Every figure above is a modeled assumption, labeled as such. Founding-cohort actuals replace this table in Q4 2026 — whichever way they land.
Expansion revenue is designed in, not bolted on: 1:1 mentor sessions ($49), parent+daughter workshops ($39), summer intensives, sibling enrollment (20% off drives multi-seat households), and year-over-year re-enrollment through age 15. Instrumented funnel targets from day one: CPL <$50 · workshop show rate 60% · trial-to-paid 35–45% · month-2 retention >80% · referral share 20% by month four.
Defensibility
"What happens when OpenAI ships this feature?" Nothing. We're not a feature.
2026 capital is right to be allergic to wrappers. This isn't one: the product is a live teacher, the same 11 classmates all year, a half-finished portfolio, and a brand parents trust with their daughters. Every new model release makes AI feel more urgent to parents — foundation-model progress grows this market and threatens none of it. AI is our subject, not our stack risk.
Trust infrastructure
COPPA-aligned architecture — parent-owned accounts, minimal child data, zero trackers in the student experience. Expensive to retrofit, it's the buying criterion for this parent, and the FTC's updated children's-privacy rules keep raising the floor beneath us.
Cohort lock-in
A girl mid-year with her teacher, her cohort, and a half-built capstone has switching costs no drop-in class can create. Retention is the product.
Category-defining IP
A 36-week, outcome-per-class AI curriculum for this exact age band, plus a brand built on the confidence-window research — the category definer, positioned before the category has a name.
The wedge, then the expansion
Cohorts are the beachhead. The asset is a five-year customer.
A girl who enrolls at 10 can be re-enrolled every year through 15 — advanced tracks, summer intensives, mentorship tiers priced above $99. Most consumer subscriptions fight churn downward; this one prices upward — the customer ages into $149+ tiers. The same family paying more each year is how a consumer subscription clears 100% net revenue retention, the single metric separating venture-scale from lifestyle. Beyond D2C: curriculum licensing to schools and after-school programs, and international girls' markets — starting with the Gulf, where the founder built her network operating in Dubai.
Year 1 — Prove the cohort
Fill founding cohorts, hit retention and completion benchmarks, capture the case studies.
Years 2–3 — Multiply, tier up
Parallel cohorts, advanced tracks, summer intensives. Expansion revenue per family starts compounding.
Years 3–5 — License, go international
B2B curriculum licensing; Gulf and international girls' markets via the founder's operating network.
The napkin math
Arithmetic on public pricing. No projections, no hockey sticks.
Every number below is multiplication you can redo on the back of this page. We publish it because a model an investor can recompute is worth ten they have to trust.
The atomic unit
12 × $99 = $1,188 MRR
One founding cohort. At standard pricing: 12 × $149 = $1,788. One teacher-hour per week delivers it, which is why the unit is legible before scale.
The stacking
100 cohorts ≈ $2.1M ARR
1,200 girls at $149/mo = $178,800 MRR. Cohorts stack linearly — no network effect required for the math to work, and every one that appears is upside.
The customer, over time
$1,788/yr → $8,900+
One school year at $149 is $1,788. A girl who joins at 10 and ages through Builder is a five-year customer approaching $9K — before any price or tier increase. That aging path is the NRR engine.
The penetration ladder
0.1% = ~$21M ARR
~12M US girls aged 10–15. One girl in a thousand at $149/mo is roughly $21M ARR. One in a hundred is $215M. We're asking you to underwrite the first thousand, not the fantasy.
The CAC bar to clear
CAC < $1,788
First-year revenue per family is the honest ceiling on acquisition cost. The founder's prior discipline was hitting exactly this kind of bar in a harder market: 15,250+ leads, 650 qualified appointments, in AI med-tech.
The comparison shelf
$149 vs. the shelf
Parents already pay in this band monthly for tutoring, music, and club sports — for skills with a flatter payoff curve than the one every parent now reads about daily. We priced into an existing habit, not a new one.
All figures are arithmetic on published pricing and US Census-scale population counts — stated as math, not as forecasts. The round exists to replace assumptions with measured CAC, retention, and completion.
The honest diligence list
What we'd stress-test if we were you
"You're pre-revenue."
True. Cohorts are forming now; the funnel, curriculum, pricing, and free-workshop pipeline are live now. Every projection on this page is labeled as modeled — and the founding-cohort fill rate over the next six weeks is the first real datapoint. Early money buys the cheapest position in the company precisely because that datapoint doesn't exist yet.
"Can one founder teach and scale?"
She doesn't scale by teaching. She scales by doing what she's done for 15 years: demand generation. Teachers are a hiring problem; a founder who fills cohorts profitably is the rare asset.
"Why won't a big player do this?"
A decade of free girls-coding programs proved the demand the way Napster proved digital music: the behavior was real, and the value accrued to whoever built the trusted paid product. Marketplaces are structurally agnostic — they can't be girls-only, one-teacher-all-year, with a quality bar. Nonprofits can't charge. Kids' coding brands are co-ed and episodic by design. The position is defensible because occupying it means abandoning their model.
"Edtech funding is depressed."
Half true. Edtech overall is flat at ~$2.8B (Crunchbase) — but AI education specifically took $4.2B in 2025, 62% of all edtech VC (HolonIQ, via EduGenius). The money didn't leave; it rotated into exactly this lane. And of 2,800+ AI-education startups, effectively all are software tools sold to schools and teachers. The trusted-school lane — live humans, one demographic, a brand parents believe — is still empty. That's the seat we're taking.
The window
Every company gets priced twice: before the proof, and after.
Outschool proved both halves of our thesis: parents pay for live online kids' classes at internet scale (a reported ~$200M in annual revenue), and its 2015 seed checks were repriced ~$3B by 2021 once the proof existed. It also proved the limit — when pandemic growth normalized, its drop-in marketplace churned and it cut staff twice in 2022. Episodic classes churn; schools retain. That churn lesson is why we built a cohort school, not a marketplace. Our proof point is concrete and near: fill rate, CAC, and week-over-week retention exist as real numbers within one quarter of the first cohort starting. Conversations now are pre-proof conversations. After the data lands — whichever way — this stops being a pre-proof price. That isn't pressure; it's how risk works.
The round
Pre-seed on a SAFE. Sized to buy one thing: proof.
Use of funds
~50% paid acquisition + funnel (the founder's home turf) · ~30% teaching staff + curriculum production · ~20% platform, children's-privacy counsel, ops.
What it buys
12 months of runway to a specific milestone: multiple full cohorts with measured CAC, retention, and completion — the exact evidence a seed round prices on.
Why early checks win
A pre-proof check is a call option — and most pre-seed options have no expiry date. Ours does: the first cohort's start. The risk premium you're paid for holding it disappears within two quarters, whichever way the data lands. Early checks also get proximity: direct advisory access to a founder who ships weekly.
Submitting the form below opens the data-room brief instantly — model walkthrough, assumptions table, and how terms work. No inbox required.
The 2026 evidence
This year's research, not last decade's. Every claim links to its source.
of US parents plan to pay for AI classes or tutoring this year. With ~50M K-12 students, that's millions of households opening a brand-new budget line in 2026.
Deloitte 2026 Back-to-School Survey, 1,207 parents →of parents say AI skills are critical to their child's future — while only 11% of schools teach AI. A 55-point gap between what parents want and what schools deliver. That gap is our market.
Codeyoung five-country parent survey, Apr–May 2026 →of schools have any student-AI guidelines, while 28% of kids already use AI for schoolwork. Adoption is outrunning oversight — parents aren't looking for another app; they're looking for an adult in the room.
Deloitte 2026 →The global kids' coding-course market, 2026 to 2032 — the category adjacent to ours on track to more than double, before "AI school" exists as a shelf. We're positioned where that budget line is heading, not where it's been.
Verified Market Reports, 2026 →of parents are concerned about AI misusing student data. Our privacy-first, parent-account, no-ads architecture isn't compliance overhead — it's the moat matching parents' #1 stated fear.
CSBA / national family survey, Apr 2026 →"Parents want their children to use AI thoughtfully — not depend on it." Jennie Williamson, EdTrust in Massachusetts — Jan 2026 poll of 1,351 parents; 59% said their child already uses AI for schoolwork. That sentence is our curriculum philosophy: builders, not dependents. The 2026 parent isn't asking whether — they're asking who they can trust.
Two minutes of your time, honestly spent.
If you invest in education, consumer subscription, or AI literacy — introduce yourself before the first-cohort datapoint exists, and follow the numbers with us as they land.